Skip to content
Homeowner Foreclosure Prevention

The Loss-Mitigation Application: How to Build a Package Lenders Approve

Most modification denials are paperwork denials. The complete checklist, the mistakes that sink applications, and the federal protections a complete file unlocks.

9 min read

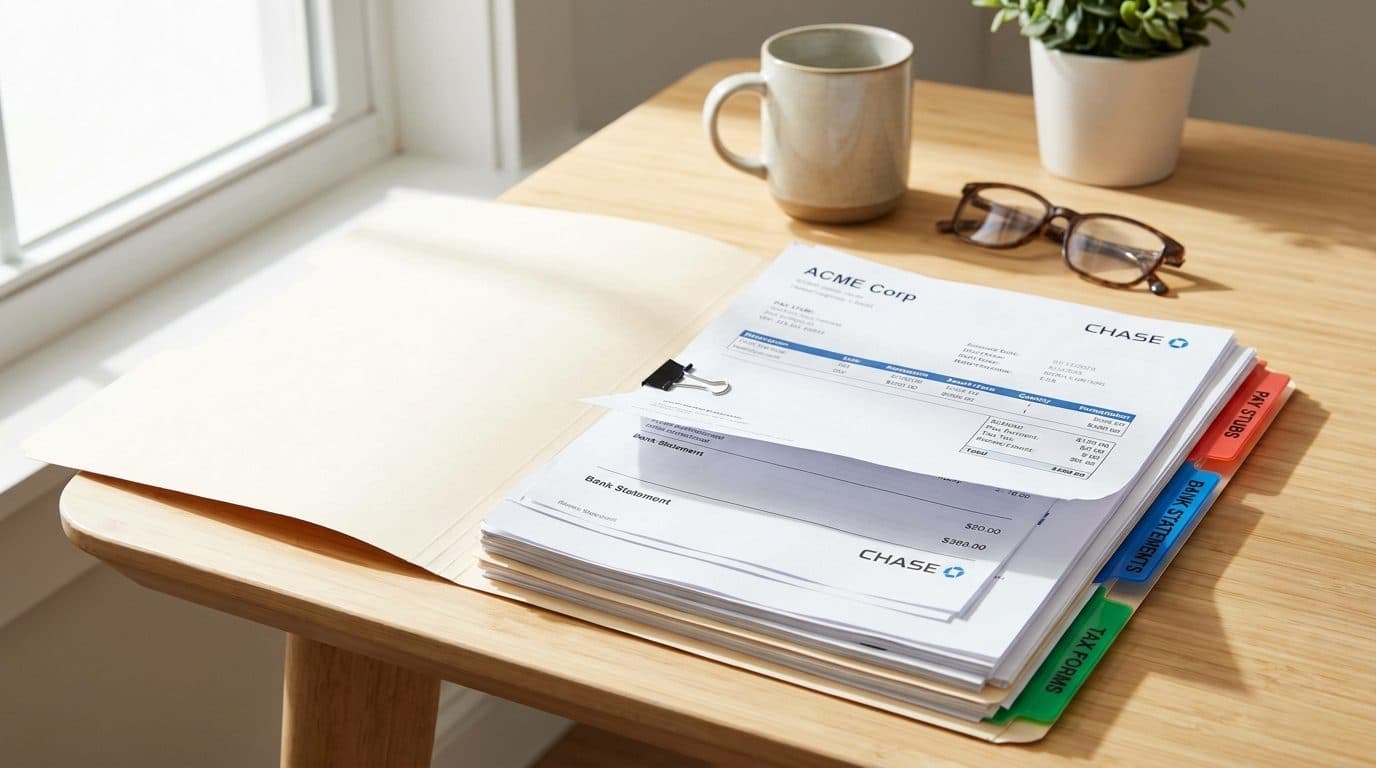
Organized folder of financial documents ready for a lender

Why 'complete' is a legal term

Under federal mortgage-servicing rules, a complete application received early enough triggers dual-tracking protections: the servicer generally cannot move for judgment or conduct a sale while your review is pending. An incomplete file triggers nothing. Servicers must tell you what's missing — but the back-and-forth burns your timeline, which is why homeowners lose months to a missing bank statement page.

The checklist

Typical requirements: the servicer's RMA/application form; a signed and dated hardship letter; last 2 pay stubs (or profit-and-loss if self-employed); last 2 bank statements, all pages, even blank ones; last 2 years' tax returns with a signed 4506-C; proof of other income (Social Security, support); a monthly household budget; and a utility bill proving occupancy.

The classic silent killers: missing bank-statement pages, unsigned letters, expired documents (most items go stale after 90 days), and unexplained deposits — annotate anything unusual.

Writing the hardship letter

One page. What happened, when, why it reduced income or raised expenses, what has changed, and what you're asking for. Attach proof where it exists — termination letter, medical bills, divorce decree. Honest and specific beats dramatic every time.

After you submit

Demand a written acknowledgment naming any missing items (federal rules require it within 5 business days). Then follow up weekly, in writing, and keep a log. If a decision comes back as a denial, you're owed the reason and — for modifications — appeal rights within set windows. Denials for 'missing documents' or 'investor restrictions' are frequently reversible; that's exactly the fight our specialists handle daily.

FAQ

Quick answers

Does a loss-mitigation application stop a foreclosure sale?

A complete application received more than 37 days before the sale generally requires the servicer to halt foreclosure steps while reviewing it. Late or incomplete applications carry no such protection — file early and complete.

General information, not legal, tax, or financial advice. Homeowner Foreclosure Prevention is not a law firm, lender, or government agency. Free HUD-approved counseling: hud.gov/counseling · 800-569-4287.

Free options review

Turn what you just read into a plan

Answer a few quick questions and a specialist will map your timeline and every option still open to you.

  • Foreclosure specialists, no pressure
  • Every option explained in plain English
  • Free consultation — no upfront fees

See your cash options

Free & confidential · no obligation

Step 1 of 40%

Where do things stand today?

Homeowner reviews

Trusted by homeowners like you

Real stories from families who stopped foreclosure with a cash offer or a lease-back — and walked away with money in their pocket.

They bought our house as-is and leased it right back to us. The foreclosure stopped and we never had to move. I still can't believe we got to stay.
JJessica T.Homeowner · TX
Auction was two weeks out. Their cash offer closed in six days and paid everything off — I walked away with money instead of a foreclosure on my record.
VVictoria L.Homeowner · FL
No repairs, no showings, no agent fees. They took the house exactly how it was and handed me a check at closing.
BBradley O.Homeowner · CO
The lease-back was a lifesaver. We stopped the foreclosure, got cash to catch up on everything else, and my kids never had to change schools.
SShannon M.Homeowner · AZ
I thought selling meant weeks of strangers walking through my house. Their cash offer meant one number, one closing date I picked, done.
JJose R.Homeowner · CA
They were honest about the numbers from the first call. Cash offer, no obligation, and money in my pocket to start over.
MMarcus D.Homeowner · GA
Behind on payments and a notice on the door. They bought it fast, paid off the mortgage, and I finally slept through the night.
PPriya N.Homeowner · NY
We didn't want to leave our home. The purchase and lease-back let us stay put and get out from under the mortgage at the same time.
KKaren S.Homeowner · NC
No pressure, no judgment. They laid out both options and let me choose. I took the cash offer and moved on with my equity intact.
TTom B.Homeowner · OH
Cash at closing, exactly like they said. It covered our moving costs and gave us a cushion to breathe again.
AAisha R.Homeowner · IL
One call and I understood both paths in plain English. They handled the lender and every deadline — I just picked a closing date.
DDaniel K.Homeowner · WA
They answered on a Saturday and treated it like the emergency it felt like. Bought the house, stopped the sale, forever grateful.
EEthan W.Homeowner · MI
They bought our house as-is and leased it right back to us. The foreclosure stopped and we never had to move. I still can't believe we got to stay.
JJessica T.Homeowner · TX
Auction was two weeks out. Their cash offer closed in six days and paid everything off — I walked away with money instead of a foreclosure on my record.
VVictoria L.Homeowner · FL
No repairs, no showings, no agent fees. They took the house exactly how it was and handed me a check at closing.
BBradley O.Homeowner · CO
The lease-back was a lifesaver. We stopped the foreclosure, got cash to catch up on everything else, and my kids never had to change schools.
SShannon M.Homeowner · AZ
I thought selling meant weeks of strangers walking through my house. Their cash offer meant one number, one closing date I picked, done.
JJose R.Homeowner · CA
They were honest about the numbers from the first call. Cash offer, no obligation, and money in my pocket to start over.
MMarcus D.Homeowner · GA
Behind on payments and a notice on the door. They bought it fast, paid off the mortgage, and I finally slept through the night.
PPriya N.Homeowner · NY
We didn't want to leave our home. The purchase and lease-back let us stay put and get out from under the mortgage at the same time.
KKaren S.Homeowner · NC
No pressure, no judgment. They laid out both options and let me choose. I took the cash offer and moved on with my equity intact.
TTom B.Homeowner · OH
Cash at closing, exactly like they said. It covered our moving costs and gave us a cushion to breathe again.
AAisha R.Homeowner · IL
One call and I understood both paths in plain English. They handled the lender and every deadline — I just picked a closing date.
DDaniel K.Homeowner · WA
They answered on a Saturday and treated it like the emergency it felt like. Bought the house, stopped the sale, forever grateful.
EEthan W.Homeowner · MI